114. Decisions subject to administrative review and procedures
(1) For the purposes of this Act, the following decisions may be subject to administrative review:-
(a) Advance ruling issued by the Department pursuant to Section 76,
(a1) Decision or order made pursuant to sub-section (8) of Section 90,
(b) Estimate made by the Department on, or decision made by it to estimate, the estimated tax payable by any person pursuant to sub-section (7) of Section 95,
(c) Decision made by the Department to order any person to submit the income return pursuant to sub-section (5) of Section 96 or Section 97,
(d) Decision made by the Department on any application made by any person for the extension of the time-limit for submission of the income return pursuant to Section 98,
(e) Assessment of tax payable by any person for any income year pursuant to Section 100 or 101, or assessment of auction expenses referred to in sub-section (5) of Section 105, or assessment of fees and interest payable by any person pursuant to Section 122,
(f) Notice given by the Department requiring any recipient to set aside amounts receivable pursuant to sub-section (2) of Section 108,
(g) Decision made by the Department to order any person holding moneys payable to the person in arrear of tax to pay the same to the Department pursuant to sub-section (1) of Section 109,
(h) Decision made by the Department to order any person to pay tax of any person due and payable on behalf of a non-resident person pursuant to sub-section (1) of Section 110,
(i) Decision made by the Department on any application made by any person for the refund of tax pursuant to sub-section (5) of Section 113, and
(j) Decision made by the Department on any application made by any person for the extension of the time-limit for filing a complaint pursuant to sub-section (3) of Section 115.
The process of examining orders or decisions made by the tax officer or the Department from an administrative standpoint and checking whether they are in accordance with the law is called administrative review. Based on such examination, where such decisions are found not to be in accordance with the law, such decisions or orders are reversed. When a lower officer has made a procedural or computational error, or an error due to negligence or lack of competence, the higher authority (the Director General) corrects it. This arrangement has been made so that, with the entire Inland Revenue Department acting as one integrated body, the taxpayer may as far as possible be provided a fair decision conveniently and promptly.
(2) Even if decision has been made by the Department on the matters mentioned in clauses (d), (i) and (j) of sub-section (1), if the Department does not give notice of the decision to the applicant within thirty days after the making of the application pursuant to Section 98, sub-section (3) of Section 113 or sub-section (3) of Section 115, the decision may be subject to administrative review as if it were a decision to reject the application.
Under Section 114(2) of the Act, administrative review petitions may also be filed against the following decisions:
(1) If a person has filed a petition requesting an extension of the deadline for filing an income return under Section 98 and the Department fails to give notice of the extension within 30 days of receipt of the petition, the petitioner may treat the petition as rejected, i.e., treat it as a decision of non-extension, and file an administrative review petition against such decision of non-extension.
(2) If a person has filed a petition for a tax refund under Section 113 and the Department fails to give notice of the decision on the petition within 30 days of filing the petition, the petitioner may treat the Department as having made a decision rejecting the petition and file an administrative review petition against such decision.
(3) If a person has filed a petition under Section 115(3) for an extension of the deadline for administrative review, and the Department fails to give notice of whether the extension was granted within 30 days of receipt of the petition, the petitioner may treat the petition as having been rejected by decision and file an administrative review petition against such decision.
(3) If the applicant does receive a notice of decision within the time-limit referred to in sub-section (2) and registers information thereof with the Department, the decision made by the Department to reject the application mentioned in that sub-section and notice thereof shall be deemed to have been served on that person on that date.
There is a difficulty in calculating the deadline for filing an administrative review petition. In all three situations under Section 114(2), the fact that the petitioner's demand has been rejected by the Department has neither been communicated to the petitioner nor is there any basis for the petitioner to know. Section 114(3) provides the solution: the petitioner shall be deemed to have received notice of the decision when the following two conditions are both met: (1) if the Department fails to give notice of the decision to the petitioner within the deadline of 30 days, and (2) on the date when the petitioner registers their information with the Department in that regard. That date shall be treated as the date on which a decision on the administrative review was made and notice of such decision was received by or given to the petitioner.
Administrative review decisions (Sec 114): the Director General re-examining whether an officer's/Department's decision is lawful, and reversing it if not.
Reviewable decisions include: advance rulings (Sec 76), WHT orders (90(8)), estimated-tax estimates (95(7)), orders to file a return (96(5)/97), refusal to extend return time (98), jeopardy/amended assessments (100/101), auction-cost & fee/interest assessments (105(5)/122), third-party set-aside/payment orders (108/109/110), refund decisions (113(5)), and time-extension decisions (115(3)).
114(2): if the Department does NOT decide an extension (98), refund (113) or review-extension (115(3)) application within 30 days, it is DEEMED rejected and itself becomes reviewable
115. Application for administrative review
(1) A person who is not satisfied with any decision subject to administrative review referred to in Section 114 may make an application to the Department against the decision within thirty days of the date of receipt of notice of that decision.
The following procedure must be completed to file a petition with the Department for administrative review:
(1) A petition must be filed only against decisions that are subject to administrative review under Section 114, if the petitioner is not satisfied with them.
(2) The petition must be filed within 30 days of receiving notice of such decision. If the deadline for filing the petition has expired for any reason, a petition requesting an extension of the deadline may be filed within seven days of the expiry of the deadline.
(3) The Department must examine a petition filed for extension of the deadline, and upon finding reasonable cause, may grant an extension of up to thirty days from the date of expiry of the deadline. The notice of such extension must be given in writing to the petitioner.
(4) There is no obligation to grant an extension. The Department may refuse to grant an extension if the reason is not found reasonable, but must give written notice to that effect to the petitioner.
(5) The petition may be written in the customary general format and must clearly state what provision of which law was violated by the decision in question, how and to what extent the petitioner was aggrieved, as well as the grounds and reasons for the review.
(6) The person adversely affected or aggrieved by the decision has the right to file an administrative review petition personally or through an authorised representative or attorney.
(7) An administrative review may be filed through an agent, provided a document showing the appointment of an agent in a legally valid manner is attached.
(8) For administrative review, it is mandatory that the petitioner has paid the full amount of undisputed tax and that the receipt showing payment of one-fourth of the disputed tax amount is attached to the petition. Otherwise, the administrative review proceedings cannot take place.
(9) Evidence supporting the claim should be attached to the petition.
(2) The application to be made pursuant to sub-section (1) shall clearly set out the reasons and grounds for such review.
(3) If the time-limit for making an application pursuant to sub-section (1) expires and any person makes an application for an extension of the time-limit within seven days from the date of expiration, the Department may do as follows:-
(a) Extend the time-limit for a period not exceeding thirty days from the date of expiration of the time-limit for making the application pursuant to sub-section (1), where there is a reasonable cause, and
(b) Give the applicant a written notice of the decision made by the Department on the application.
If the Department grants an extension, written notice must be given to the petitioner. The decision on the extension must be made within 7 days of the petition for extension being received. If a decision of non-extension is made, it may itself be subject to administrative review under Section 114(2).
(4) The making of an application pursuant to sub-section (1) shall not be deemed to affect the implementation of the decision mentioned in sub-section (1) of Section 114.
Generally, the filing of an administrative review petition does not in itself prevent the implementation of the disputed decision. The filing of a petition for administrative review shall not be deemed to affect the implementation of the decision mentioned in Section 114(1).
(5) Notwithstanding anything contained in sub-section (4), the Department may postpone or otherwise affect the decision made pursuant to sub-section (1) of Section 114 pending the settlement of the application made by any person pursuant to sub-section (1).
(6) A person who makes an application pursuant to sub-section (1) shall pay the total amount of undisputed tax and one-fourth of the disputed tax out of the assessed tax amount.
(7) The Department may do as follows on an application made by any person pursuant to sub-section (1):-
(a) Accept or reject, fully or partly, the matters mentioned in the application, and
(b) Give the applicant a written notice of the decision on the application.
If the petition filed by the petitioner is found to be reasonable, the Department may wholly or partly reverse the decisions made against the petitioner. Similarly, if not found reasonable, the Department may make a decision not to accept the petitioner's demand. Whatever decision is made during the administrative review, the Department must give written notice thereof to the petitioner.
(8) If the Department fails to give the applicant notice of a decision on the application within sixty days of the date on which the application was made pursuant to sub-section (1), the applicant may make an appeal to the Revenue Tribunal pursuant to Section 116.
The Department must complete the examination of the petition for administrative review, make a decision within 60 days of the date of filing, and communicate the decision to the petitioner. If the Department fails to give notice of the decision within that period, the petitioner may inform the Department in writing to the effect that they consider the Department to have made a decision on their petition, and may treat the petition as having been rejected. For that purpose, the date on which the petitioner registers such information shall be deemed to be the date on which a decision on the administrative review was made and notice of such decision was received or given to the petitioner.
(9) If an appeal is made pursuant to sub-section (8), such person shall give written information to the Department, enclosing a copy of the appeal, within fifteen days of the date on which the appeal was filed.
If an appeal to the Revenue Tribunal is filed on the basis of the Department's deemed rejection under Section 115(8), it is mandatory for the petitioner to register written information with the Department about what the petitioner considers to have been decided, within fifteen days of filing the appeal, attaching a copy of the appeal letter.
Application for administrative review (Sec 115): file with the Department within 30 DAYS of receiving notice of the decision, stating the grounds. If the deadline lapses, apply within 7 days for an extension of up to 30 more days (reasonable cause; decided within 7 days).
MANDATORY DEPOSIT (115(6)): pay 100% of the UNDISPUTED tax PLUS 25% of the DISPUTED tax - otherwise the review cannot proceed.
Filing does not stay the decision (115(4)), though the Department may stay it (115(5)).
The Department decides within 60 DAYS and notifies in writing; if it does NOT decide within 60 days, the applicant may treat it as rejected and appeal to the Revenue Tribunal (115(8))
116. Appeal to the Revenue Tribunal
(1) A person who is not satisfied with any decision made by the Department pursuant to Section 115 may make an appeal to the Revenue Tribunal under the Revenue Tribunal Act, 2031 (1974).
Under Section 116 of the Act, an appeal to the Revenue Tribunal lies against the following decisions:
(1) a decision made by the Department under Section 115 on a petition filed for administrative review; and
(2) if the decision that may be subject to administrative review under Section 114(1) has been made by the Director General himself, such decision made by the Director General.
The right to appeal is governed by law. Through appeal, it is examined whether the decision made by the lower officer or body is just and lawful, and if found to be contrary to justice and law, such decision is reversed. The procedure for filing appeals and the authority to make decisions on appeals are governed by the Revenue Tribunal Act, 2031 and the Revenue Tribunal Rules, 2030.
(2) A person who makes an appeal pursuant to sub-section (1) shall register a copy of the appeal with the Department within fifteen days of the date of filing the appeal.
This registration requirement ensures the Department is informed of the appeal and can participate as the respondent in the Revenue Tribunal proceedings.
(3) The making of an appeal pursuant to sub-section (1) shall not be deemed to affect the implementation of the decision mentioned in sub-section (1) of Section 114.
Generally, according to accepted principles of justice, when an appeal is filed, the lower decision cannot be implemented. However, Section 116(3) of the Income Tax Act, 2058 states that filing of an appeal shall not be deemed to affect the implementation of the decision mentioned in Section 114(1) that may be subject to administrative review. Therefore, a decision against which an appeal has been filed can be implemented. However, if the Revenue Tribunal or court has issued an immediate stay order, the Department's decision shall be stayed (remain in abeyance) in accordance with such order.
(4) Notwithstanding anything contained in sub-section (1) of Section 114, if the Director General has made a decision subject to administrative review as mentioned in that sub-section, an appeal may be made to the Revenue Tribunal.
(5) Upon filing an appeal to the Revenue Tribunal pursuant to sub-section (1), the undisputed amount of the assessed tax shall be submitted and fifty percent of the disputed tax amount, charge and fine, or a bank guarantee of such amount, shall be provided.
(6) In computing the deposit amount or bank guarantee pursuant to sub-section (5), the twenty-five percent of the tax amount submitted to the Department for administrative review shall also be included.
(7) The bank voucher deposited in the deposit account at the Office of the Comptroller and Accountant General in the name of the concerned office pursuant to sub-section (5), or the bank guarantee letter equal to such amount, shall be submitted together with the appeal.
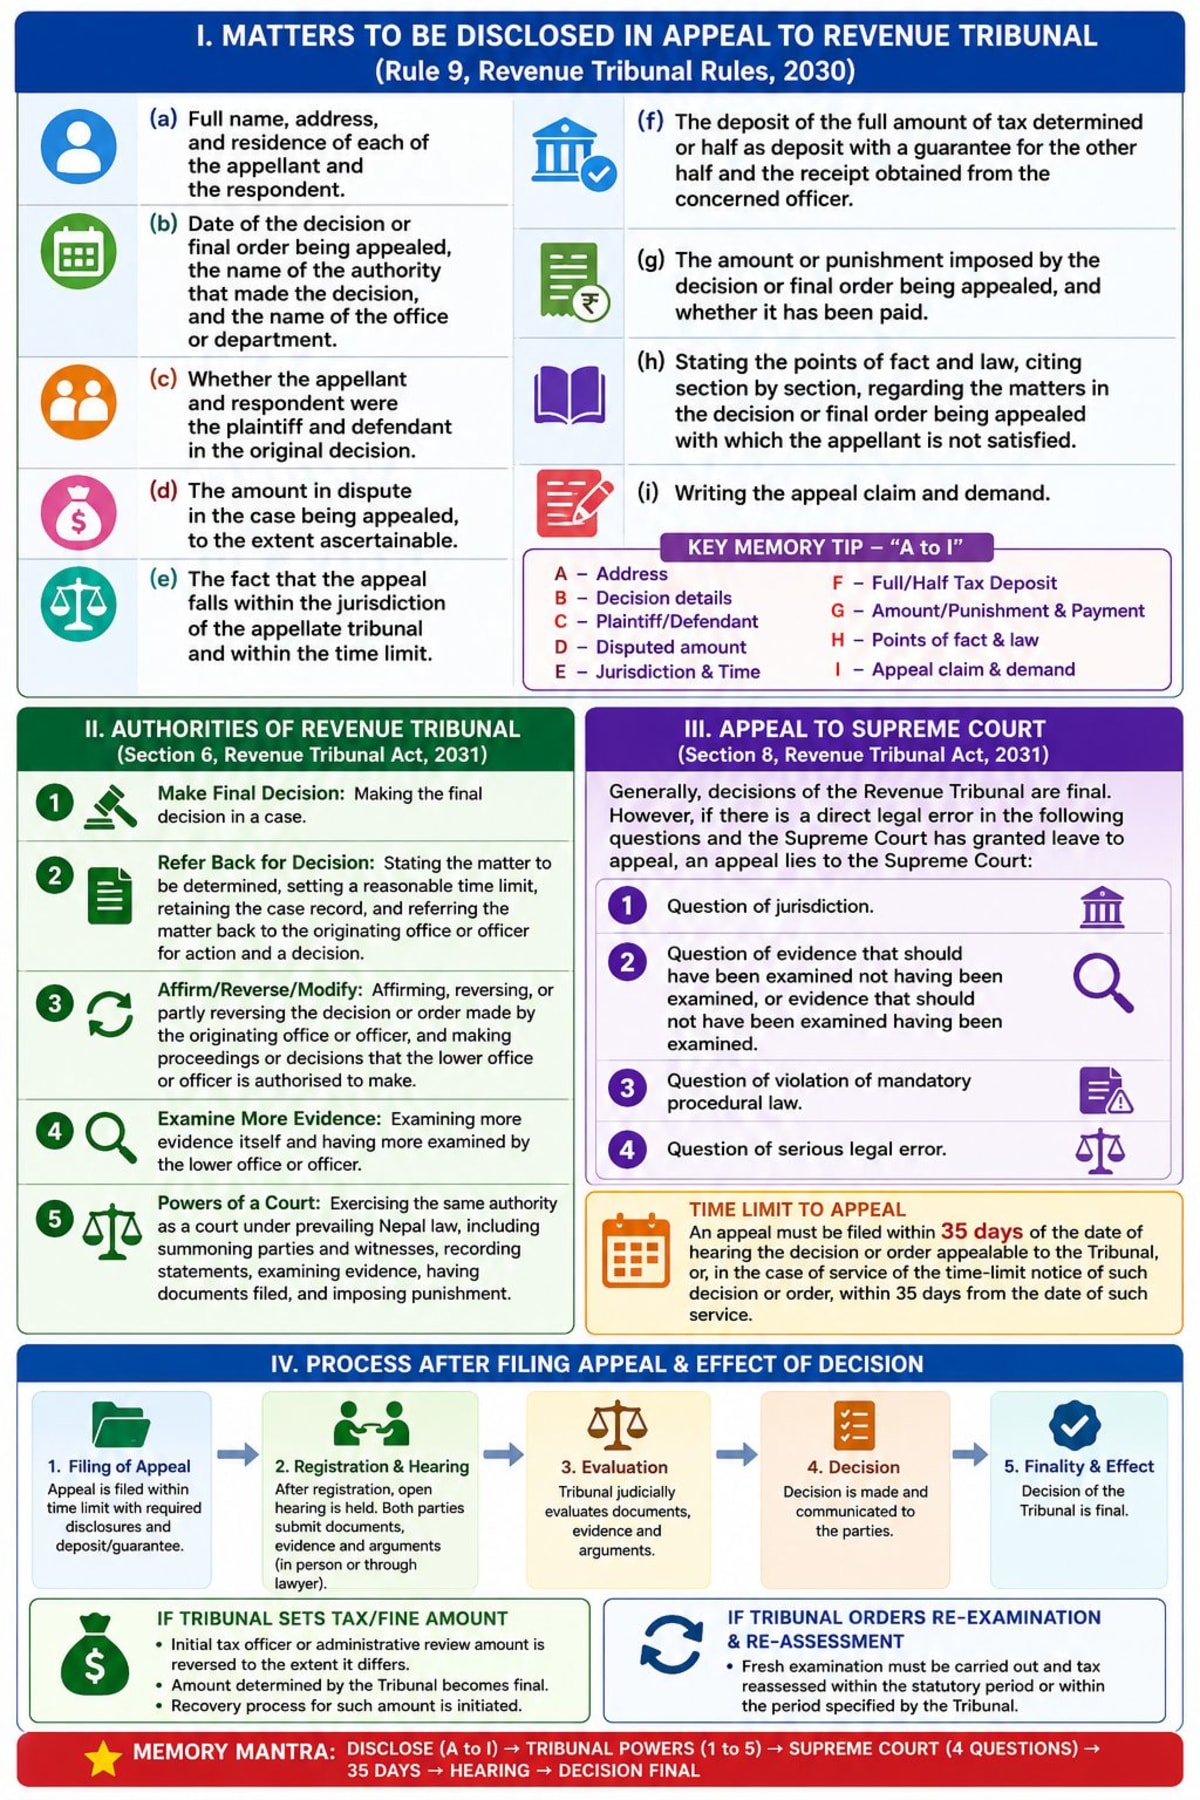
Appeal to the Revenue Tribunal (Sec 116): a person dissatisfied with the Department's Sec 115 decision may appeal to the Revenue Tribunal (under the Revenue Tribunal Act, 2031) within 35 DAYS of the decision/notice, and must register a copy with the Department within 15 days of filing.
MANDATORY DEPOSIT (116(5)): 100% of the undisputed tax PLUS 50% of the disputed tax, fees & penalties (cash or bank guarantee) - the 25% already deposited for administrative review counts toward this 50% (116(6)), so only the balance is needed.
Filing does not stay the decision unless the Tribunal/court orders a stay.
Where the Director General personally made the original decision, the appeal goes DIRECTLY to the Tribunal, skipping administrative review (116(4)).