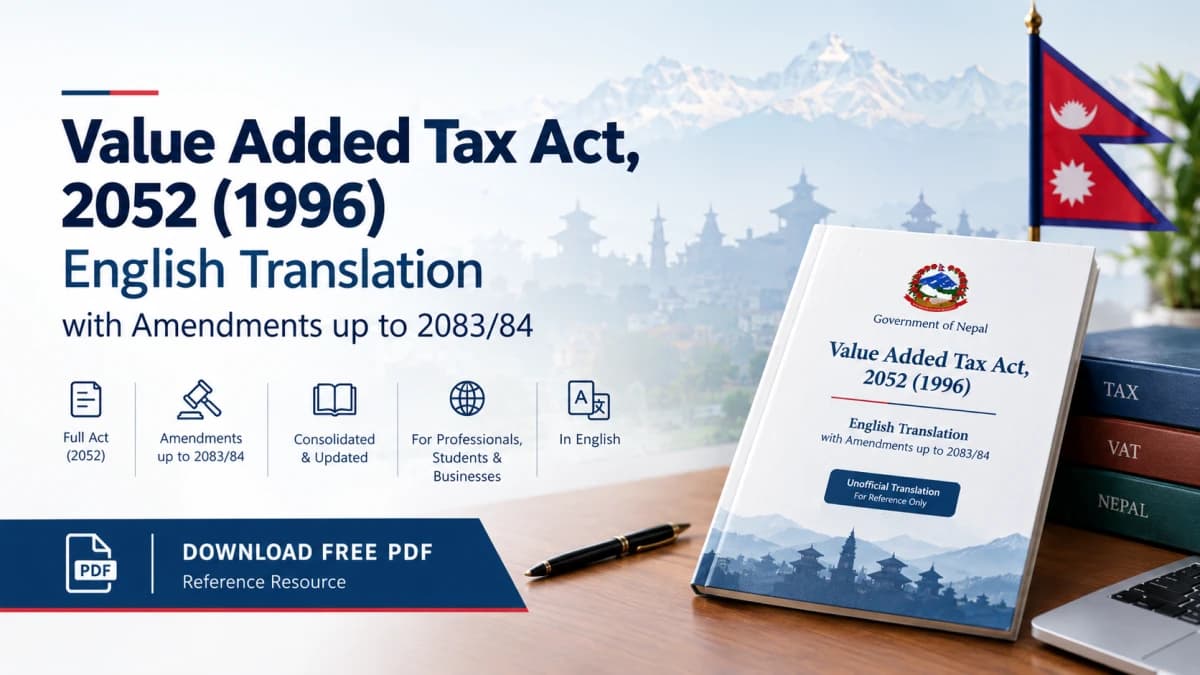
For the convenience of tax professionals, Chartered Accountants, students, businesses, researchers and other users of Nepalese tax legislation, I have prepared an English translation of the Value Added Tax Act, 2052 (1996), incorporating amendments applicable up to FY 2083/84.
The Value Added Tax Act, 2052 is one of the principal tax laws governing the imposition, collection and administration of Value Added Tax (VAT) in Nepal. The Act covers important areas including VAT registration, taxable transactions, tax collection, input tax credit, invoicing, returns, assessment, recovery, refunds, offences and penalties, among other matters.
What this resource contains
This translated version is prepared with the objective of making the VAT Act more accessible to readers who are more comfortable working with English-language legislation.
It incorporates:
The Value Added Tax Act, 2052 (1996);
Amendments made to the Act up to FY 2083/84;
Updated provisions arranged in a consolidated form for easier reference; and
English terminology intended to remain consistent with the language commonly used in Nepalese tax and accounting practice.
Who may find this useful?
This resource may be particularly useful for:
Chartered Accountants and tax professionals;
CA students and other accounting and finance students;
Tax practitioners and consultants;
Businesses and finance teams;
Legal and tax researchers;
Foreign investors and professionals working with Nepalese tax laws; and
Anyone seeking to understand Nepal's VAT legislation in English.
Download the English Translation
VAT Act 2083/84 (2026/27)The PDF is provided as a free reference resource for educational, professional and research purposes.
Important Note
This is an English translation prepared for reference and ease of understanding. It should not be treated as an official English version of the legislation. In case of any discrepancy, ambiguity or conflict between this translation and the legislation published in Nepali through the official legal sources, the official Nepali text shall prevail.
Users are advised to refer to the latest legislation, notifications, rules, procedures and other official publications issued by the Government of Nepal and the Inland Revenue Department when making compliance or legal decisions.
I hope this resource will make Nepal's VAT legislation easier to access and use for students, professionals and businesses.
— CA Roshan Poudel